Remortgaging - Investment

Remortgaging to buy another property

7 min read

If you've been paying off your mortgage for a few years, you might have more buying power than you realise. Remortgaging lets you unlock the equity in your current home to fund a second property — without saving a separate deposit or selling up. This guide explains your options for structuring the deal, what it costs, and how to work out if it's affordable for your situation.

  • Smiling person with a beard and short hair wearing a black shirt, standing against a plain light gray background.
    Mo Amin

    Conveyancing Team Manager

    Updated on

    Published

holiday home along the North Kent coast, perfect for a second home

Key takeaways

  • You can remortgage your current home to buy a second property using the equity you’ve built up.

  • Most people use remortgaging to fund a buy-to-let, second home, or holiday let.

  • Your eligibility depends on affordability, credit history, and loan-to-value (LTV).

  • Taking professional advice is important, as monthly repayments and risks will increase.

If you’re thinking of remortgaging to buy another property, our guide explains how it works, so that you can make an informed decision about your future.

In this article:

Can you remortgage to buy another property?

Yes, you can remortgage to purchase another property. Lenders widely accept using the equity built up in your current home as a deposit for an additional property, such as a buy-to-let investment, second home, holiday let, or commercial real estate. It can also form part of a let-to-buy strategy, where you let out your current home and purchase a new primary residence.

To approve this type of remortgage, lenders will assess:

  • Your available equity: This is the most critical factor, as you must leave enough equity in your current home while releasing a sufficient amount to fund the new deposit.

  • Affordability and credit score: Lenders will review your income, existing debts, and credit history to ensure you can support the increased loan size.

  • Loan-to-Value (LTV) ratio: A lower overall LTV across your properties will grant you access to better interest rates and more flexible deal options.

  • Intended use of funds: Lenders evaluate the specific risk associated with your new purchase, as different rules, criteria, and tax implications apply to buy-to-let investments versus personal second homes.

If you are unsure, we suggest that you speak to a mortgage adviser to see if you are eligible, or read our guide which explains how remortgaging works.

How does releasing equity to buy a second home work?

Equity is the money you own in your property — what you've paid off your mortgage plus any increase in home value. When you remortgage, you can release this equity by borrowing more than you currently owe. This can go towards a deposit on a second home, or, if it’s enough, to buy outright.

Here's how it works:

Let's say you bought a house for £200,000 and borrowed £160,000. You initially own £40,000 of it (your equity).

Fast forward five years. Your house is now worth £230,000 and you owe a remaining £140,000 on your mortgage. The difference between these numbers is £90,000, which is what you now own in equity.

When you remortgage, instead of keeping your loan at £140,000, you increase it to £170,000. That £170,000 pays off the £140,000 you owe, leaving you with £30,000 in cash (released equity).

You still own £60,000 in equity, which is locked in the home. (£90,000 - £30,000 cash)

You use that £30,000 as a deposit on a second property, then take out a separate mortgage for the rest.

Lenders will check if you can afford both payments. You'll also pay conveyancing fees for both the remortgage and the second property purchase, so budget accordingly.

What are the options for remortgaging to buy a second home?

Instead of saving up cash for a deposit on a second home, you are releasing the cash value locked inside your current house as your down payment.

Because you are balancing the finances of two separate properties, lenders will look at your application entirely differently than a standard remortgage. You have three main ways to structure this type of financing:

  • One large mortgage: If you have an immense amount of equity, you can replace your existing mortgage with a single, much larger loan. This loan pays off your old balance and gives you enough cash to buy the second property completely outright. You end up with just one monthly payment secured against your first home.

  • Two separate mortgages: This is the most common route. You remortgage your first home to pull out a cash lump sum (for example, £40,000). You then take that cash and use it as the deposit to launch a brand-new, second mortgage on the new property. You will now have two separate monthly mortgage payments to manage.

  • Second charge mortgage: If your current mortgage has a great interest rate that you don't want to lose, or if your early repayment charges are too high, you can keep your original mortgage exactly as it is. Instead, you take out a separate "second charge" loan secured against your equity to act as the deposit for your next property.

Taking equity out of your house to buy another property

With every month that you pay towards your mortgage, you are building up equity in your home by reducing how much you owe. As the equity in your home increases, so does the amount you can release. This equity can often be used as a deposit for a second property when remortgaging.

If you are unsure about how much equity you might have built up in your home, you can get a valuation and just deduct your outstanding mortgage balance. A mortgage adviser will be able to help you with this calculation.

the front of a picturesque cottage being remortgaged in order to complete some home improvements

What is remortgaging and how does remortgaging work?

July 19th 2024-6 min read

Remortgaging is where you switch your mortgage deal, usually if your current deal is nearing the end. Learn more in our helpful guide.

Explore the steps you need to follow to remortgage

Understanding the costs of remortgaging and multi-property financing

Releasing equity to buy an additional home involves a much more expensive set of fees than standard remortgaging because you are executing two transactions at once. You must budget for:

  • Dual conveyancing fees: If you’re changing lender, you will pay legal fees for the remortgage on your first home, plus standard purchase conveyancing fees for buying the second property.

  • Higher rate stamp duty: In the UK, buying a second home or buy-to-let attracts a stamp duty surcharge (an extra tax on top of standard rates for owning multiple properties). Learn more about stamp duty on second homes.

  • Independent valuation costs: Unlike standard remortgages where a lender might use a quick automated valuation, pulling physical cash out means a surveyor will likely need to perform a strict, in-person assessment of your home's structure.

Is it a good idea to remortgage to buy another property?

When remortgaging your current home to buy another property, your monthly repayments are likely to be significantly larger than they were – you will have a second mortgage to repay.

We advise that you speak to a mortgage adviser to make sure it makes financial sense. They’ll go through some affordability checks with you, including a credit check and how much you could potentially borrow. They will also discuss with you whether you can afford to pay the higher repayments on your current wage, as failure to do so may result in loss of both properties.

You can also find more helpful information in our article 'What is remortgaging and how does remortgaging work?'

Risks to consider

Remortgaging to buy another property comes with certain risks. Taking on a larger mortgage increases your financial obligations, which can impact your financial stability. If interest rates rise, variable rates can lead to higher repayments, potentially straining your budget. Changes in the property market could affect the value of both your current home and the new property, which is something to bear in mind if you plan to sell in the future.

There's also the potential risk of repossession – if you're unable to keep up with the higher repayments, you could risk losing both homes. Before proceeding with remortgaging, you need to carefully weigh these risks against the potential benefits.

A mortgage adviser can help you assess these risks and explore alternatives before you commit.

Remortgaging to buy a second home when you are self-employed?

Being self-employed doesn’t prevent you from releasing equity for a second home, but it's more complex. Lenders need to prove your income can support two mortgages at once. You'll need accounts from the last two years, and they'll assess your affordability based on whether you can cover both payments. Your mortgage adviser can help you find lenders who understand self-employed income and are willing to lend in this scenario.

Can you remortgage to buy another home if you have a poor credit rating?

It's harder, but not impossible. Lenders have to assess your risk across two properties and two mortgages, so they'll be cautious. You'll likely need more equity in your first home to release, or a larger deposit for the second property to offset the credit concerns.

Specialist lenders do work with poor credit, but they're rarer for dual-mortgage scenarios. Speak to a mortgage adviser — they can assess whether lenders will consider you and what terms they might offer.

How to remortgage a buy-to-let property to expand your investment portfolio

Many landlords use remortgaging as a way to grow their property portfolio without selling existing investments.

The majority of landlords will have interest-only mortgages, where the capital of the property isn’t paid back until the end of the mortgage. As a result, lenders typically offer 85% mortgages if they wish to remortgage an investment, which is calculated by assessing the rental income of the property.

Lenders may wish to see signed tenancy agreements, as well as bank statements to show evidence of income for the property you wish to remortgage.

Find out more about buy-to-let and investment property options.

Ready to take the next step?

If you decide to take the plunge and buy that second property, you’ll need a conveyancer to deal with the legal side of your remortgage and the purchase of the second property. Get a personalised conveyancing quote for your remortgage today.

investor looking at his conveyancing quote from my home move conveyancing for his next house purchase

Remortgaging to buy another property FAQs

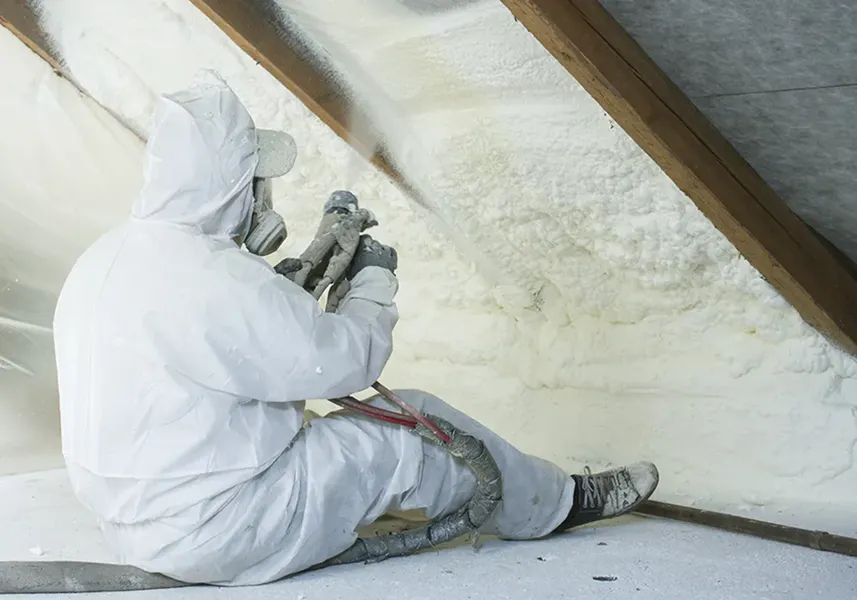
Worker in protective gear sprays foam insulation in an attic, seated on the floor, surrounded by wooden beams and white insulating foam.

Important update

Insulating foam spray

Remortgaging a property that has spray foam insulation can come with challenges. Recently, many mortgage lenders are having concerns about spray foam because of its potential to impact ventilation and roof structure.

This means that having spray foam insulation could limit your remortgaging options or require additional checks to satisfy lenders. To avoid complications, we recommend working with a surveyor who can assess the condition of the spray foam and provide a report that reassures both you and potential lenders.

Share this post

Contact

We're here to help

Get in touch with one of the team

Conveyancing team

If you would like to speak to your conveyancer, please log in to your eWay account where you can find their contact details.

  • Monday - Friday

    9am - 5pm

Move Specialist team

If you would like to get a new quote or discuss a previous one, please call our Move Specialists on

  • Monday - Friday

    9am - 5pm

General Enquiries

If you would like to email us, please send it to the following email address:

  • Monday - Friday

    9am - 5pm